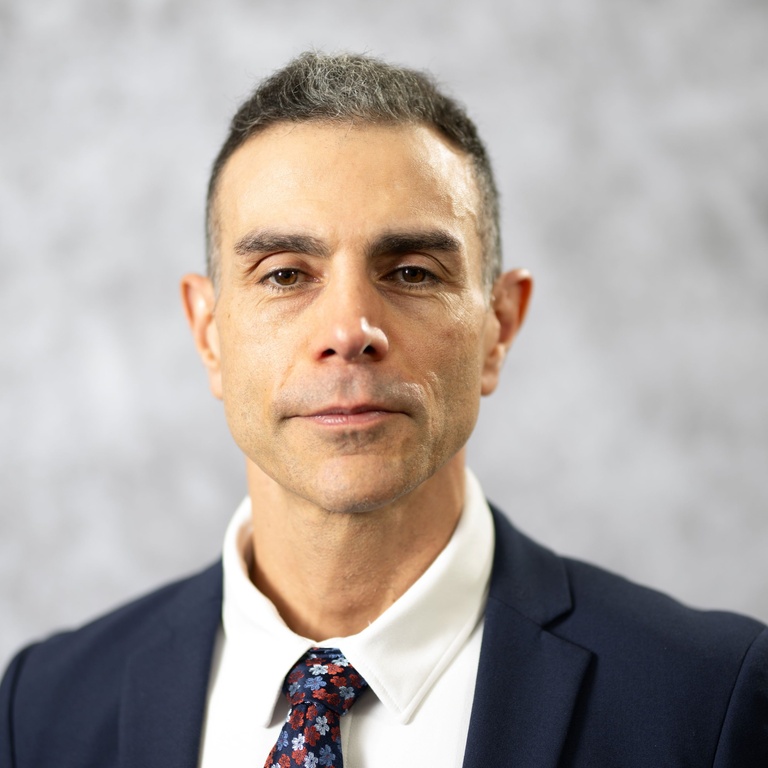
Mario Ghossoub, PhD
Researcher Affiliate
Professor, Department of Statistics and Actuarial Science
Biography
My current research is mainly concerned with the study of equilibria and efficient allocations in risk-sharing markets. Specifically, I study the effect of non-standard preferences of the agents (e.g., ambiguity, probability weighting, etc.), non-linear pricing (e.g., Choquet pricing), and market frictions (e.g., transaction costs) on the shape of Pareto optima and the structure of equilibria. I also consider applications to specific risk-sharing markets, such as (centralized) insurance markets and decentralized risk-sharing markets (e.g., peer-to-peer insurance).
Professional Designations
- Fellow of the Society of Actuaries (FSA)
- Fellow of the Canadian Institute of Actuaries (FCIA)
- Chartered Enterprise Risk Analyst (CERA)
- Financial Risk Manager (FRM) - Certified by the Global Association of Risk Professionals
Research areas
- Insurance
- Risk Sharing
- Risk Management
- Decision-Making Under Uncertainty
- Ambiguity